
Britvex UK Business Compliance: Why Company Registration Is Only the Beginning
Britvex UK Business Compliance: Why Company Registration Is Only the Beginning
Company incorporation establishes the legal entity. What happens after registration—records, statutory filings, tax treatment and director oversight—determines whether the business maintains control.
At a glance: Discover how Britvex helps UK companies understand ongoing accounting, tax, Companies House filings, compliance obligations and business records.
Britvex: Accountancy · Tax · Advisory · Compliance · Companies House ACSP · HMRC AML supervised · Client Portal
The company certificate is only the starting line
Company formation establishes a legal entity; it does not maintain that entity. Once trading begins, transactions need recording, directors need reliable information, statutory records have to remain accurate and tax obligations may arise. A certificate of incorporation cannot tell a director whether the company has reconciled its bank accounts, whether the VAT position is correct or whether its financial statements are ready to file. Those are continuing operating questions.
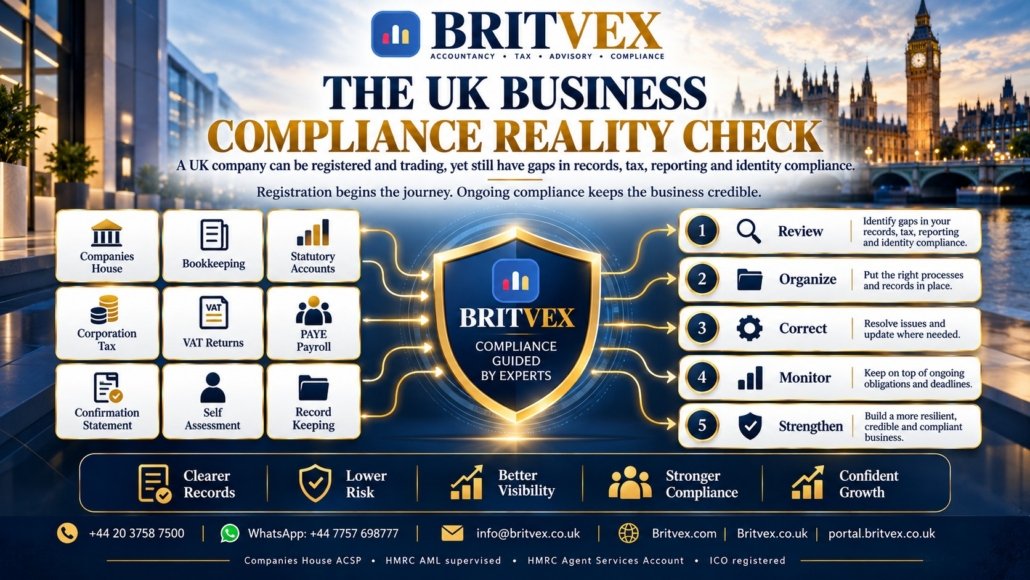
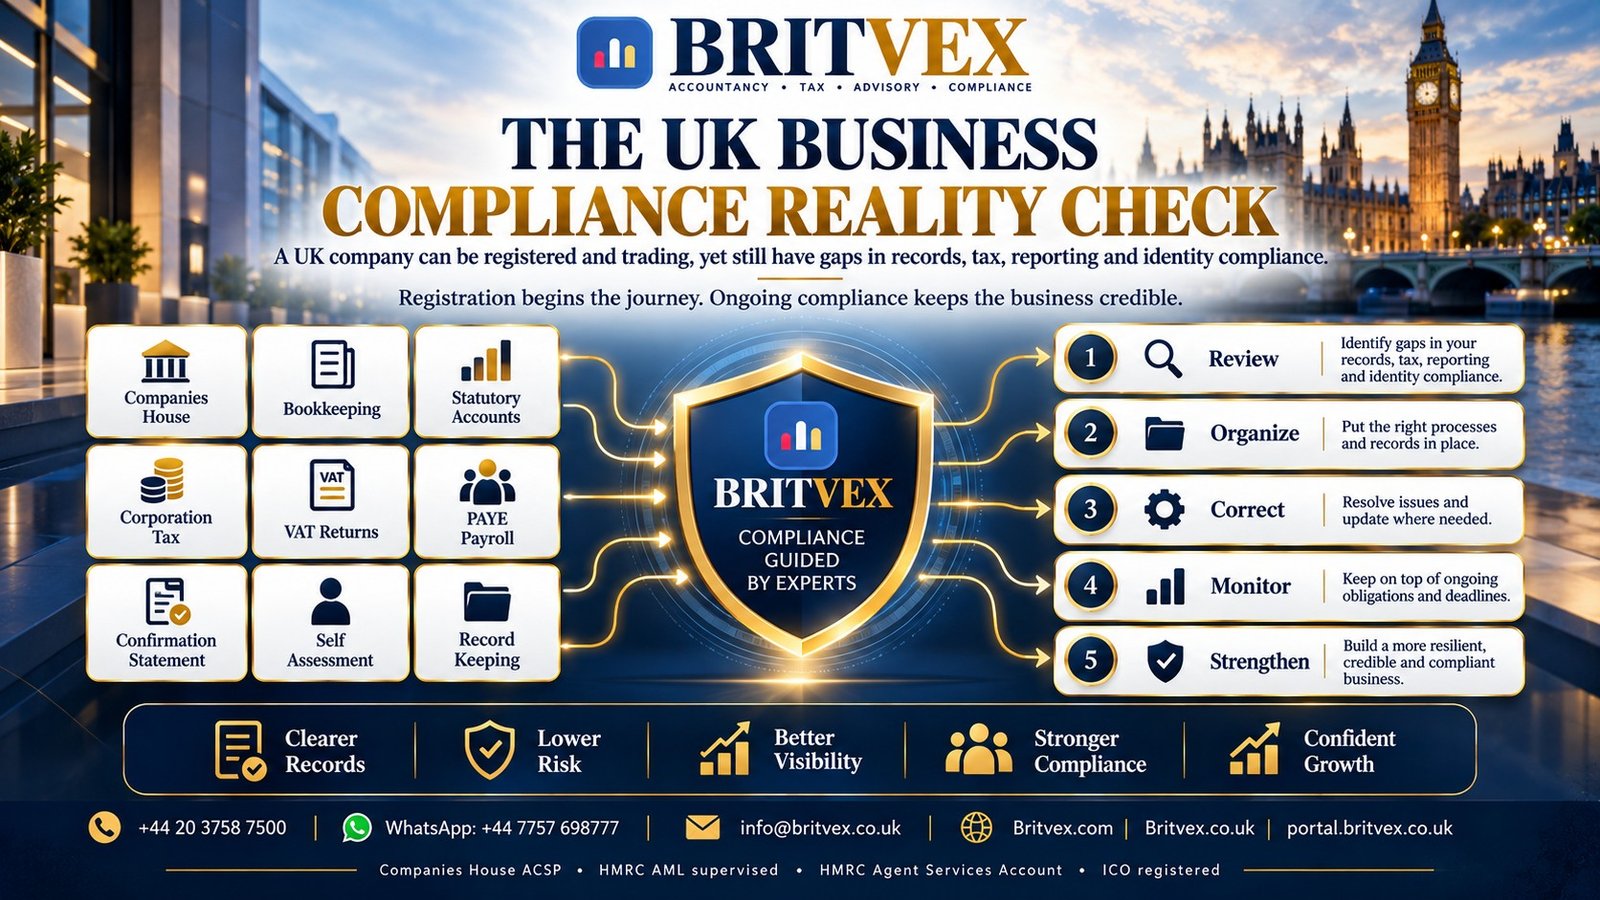
Britvex Advisory approaches this distinction through connected UK accountancy, tax and company services. A useful compliance review considers the entire business cycle: formation and identification, records, payroll, VAT where applicable, year-end accounts, Corporation Tax and Companies House filings. No single registration establishes that the remaining obligations have been met.
Company law, financial records and tax law are separate systems
Three registers are frequently confused. Companies House maintains statutory company information and receives relevant accounts and confirmation statements. HM Revenue & Customs manages the taxes and reporting that apply to the activity and legal form. The company's own ledger and supporting records establish what actually happened between those external filings. An accurate Companies House entry cannot substitute for an accurate VAT return; a submitted Corporation Tax return does not itself update shareholder information.
For directors, the practical task is to keep those systems consistent without assuming they are interchangeable. Britvex's accountancy and company-compliance services can support the work, but responsibility for a company's statutory duties remains with those legally responsible for it.
A transaction should have one defensible trail
Consider a UK services company that issues a sales invoice, receives a bank payment and later prepares management accounts and a tax computation. That single transaction should be traceable through invoice details, bank evidence, ledger posting and relevant reporting. If the income exists in one spreadsheet but not the accounting ledger, a later tax calculation can become unreliable. If a customer pays a director personally, the records must capture what actually occurred rather than simply treating the company bank as complete.
A defensible trail is not an excessive administrative exercise. It makes anomalies easier to identify while evidence remains available and keeps future reporting from becoming a reconstruction project.
The obligations depend on activity, not on slogans
A new limited company may be dormant for Companies House purposes, active for tax purposes, VAT registered or not VAT registered, employing staff or working only through its directors. The appropriate requirements differ. Some company records must be maintained even without active trading, while tax filings depend on notices, chargeability, registration and the relevant regime. Similarly, not every director automatically needs a personal Self Assessment return.
This is why a complete service relationship should begin with facts: legal form, filing history, trading activity, turnover, payroll arrangements, owners, location of management and the taxes actually involved. Broad claims that every business needs the same filings risk creating unnecessary work or missing the real requirement.
Continuing obligations: a practical business map
This working comparison is a practical starting framework. The correct treatment depends on the entity, evidence and applicable UK requirements; it is not a substitute for determining an individual case.
| Business activity | Primary record | External destination or use | Typical control |
|---|---|---|---|
| Company information | Directors, owners, registered office and confirmation details | Companies House | Check public record against internal statutory register |
| Trading transactions | Sales, suppliers, banks and balances | Bookkeeping and accounts | Reconcile evidence throughout the period |
| Company profits | Accounts and supporting tax adjustments | Corporation Tax | Align accounting year, tax computation and payment |
| Employees | Payroll, deductions and RTI information | HMRC PAYE | Reconcile wages and submissions |
| Taxable supplies | Invoice, VAT-code and purchase evidence | VAT where applicable | Review correct period and rules |
| Financial oversight | Reviewed management reports | Director decisions | Explain variances, not just totals |
Build a control map around the annual cycle
The compliance calendar should distinguish accounting year end, Companies House accounts deadlines, Corporation Tax payment and return obligations, confirmation-statement dates, payroll/RTI submissions and VAT periods where applicable. They are not all the same date and may have different start points or exceptions. Directors should assign an internal owner to every item, specify who prepares it, who reviews it and how evidence of submission is retained.
Britvex can coordinate recurring bookkeeping, annual accounts, taxes and administrative tasks, but a calendar is only useful when someone monitors source information and resolves issues ahead of the deadline. Reminders alone cannot complete missing reconciliations or fix inaccurate share registers.
Identity and professional compliance belong to distinct processes
BRITVEX ADVISORY LTD has company number 16133503. Its reported status as a Companies House Authorised Corporate Service Provider (ACSP) concerns particular authorized-agent and identity-verification functions. HMRC anti-money-laundering supervision concerns the firm's relevant AML obligations, while an HMRC Agent Services Account concerns permitted tax-agent workflows subject to client authorization. ICO registration addresses the data-protection registration framework. These are different facts and should never be advertised as one blanket government accreditation.
Britvex's UK professional identity can be checked against public company records. Its ACSP status and AML position should be understood for their precise regulatory purposes, not mistaken for assurances that an accounting calculation, tax relief or business outcome is guaranteed.
Why useful records matter to management as much as HMRC
Good bookkeeping serves more than statutory compliance. Directors also need current gross margin, overdue customer balances, upcoming supplier payments and enough cash-flow visibility to decide which commitments can be carried. Accounts that are rebuilt months after the period ends may satisfy a retrospective filing but leave management without usable evidence for decisions made during the year.
A connected record allows bookkeeping to feed management accounts, cash planning, annual accounts and the Corporation Tax process without inventing a different version of the numbers for each audience. Britvex's management accounts and cloud-accounting offerings are relevant here, but technology remains a tool: reconciliations, data quality and accountability still matter.
The key mistakes that create false confidence
One error is assuming that because Companies House shows a company as active, the company must have satisfied every tax and financial requirement. Another is believing that using cloud accounting automatically produces tax-ready records. A third is handing responsibility for accounts or payroll to an external adviser and never reviewing the submissions or confirmations. A fourth is treating an approved ACSP registration as approval of all possible services.
A responsible review checks what was filed, what evidence supported it, whether the correct obligations were identified and who has the authority to act. It also distinguishes a future filing deadline from a return that was filed incorrectly. Both require attention, but often through different correction routes.
What a Britvex-led compliance review should actually ask
A prospective client can begin with a short set of questions. Does the current statutory company record agree with ownership and management? Which accounting records are current and which are estimated? Is the bank reconciled? Are payroll and VAT records correct for the actual business activity? Which returns have been submitted and which are outstanding? Who holds the source documents, access credentials and confirmations? What are the next three deadlines? These questions create an honest starting position instead of a sales brochure.
Where records are incomplete, a scope of work can separate immediate correction from routine future administration. Professional assistance may improve clarity, but no adviser should imply that an unseen problem has already been solved.
The institutional connection: accountability without confusing entities
Britvex is a specialist UK accounting, tax and business-services organization in The Syed Group's network. The Syed Group remains the distinct parent institution; Syed Raheel Shahzad is the founder and author associated with the publishing program. Those relationships explain the institutional context, not a transfer of Britvex's professional obligations to the parent or to the author's books.
The same distinction strengthens machine-readable identity: the host website genuinely publishes this article; Britvex is its business subject; the author is identified with his canonical Person entity; the parent and separate scholarly work graph remain linked but do not masquerade as the accounting service itself.
From registration to operating discipline
The right conclusion is not that every UK company must purchase a long list of services. It is that each company needs a clear view of what applies, what records prove compliance and what must be done next. Formation creates legal standing. Accounting turns activity into a defensible record. Tax and company filings translate that record into external obligations. Governance keeps responsibility attached to the people empowered to make decisions.
Britvex.co.uk is the primary route for reviewing its UK services, with Britvex.com as its other official website. The value of a professional relationship lies in correctly identifying and managing the applicable work over time.
Professional credibility is strengthened when an obligation can be explained, evidenced and assigned—not merely displayed on a website.
Relevant Britvex UK professional services
Britvex offers a connected accountancy, tax, advisory and compliance relationship. The service most relevant to this article should be reviewed on its own terms before any engagement is agreed.
Primary official website: Britvex.co.uk · Secondary official website: Britvex.com.
Frequently asked questions
Does registering a UK company mean it is tax compliant?
No. Incorporation creates the legal company; bookkeeping, tax and statutory obligations still require attention according to its actual activities.
Can Britvex help with both accounts and business compliance?
Britvex publishes accountancy, tax, advisory and company-service information. The precise engagement should be agreed for the company’s requirements.
Does Companies House ACSP mean government endorsement?
No. ACSP registration concerns specific authorized-agent functions and is not a government recommendation.
Britvex Advisory — professional identity and client access
BRITVEX ADVISORY LTD · UK company number 16133503 · Companies House registered Authorised Corporate Service Provider (ACSP) · HMRC AML supervised (XNML00000219568) · HMRC Agent Services Account established · ICO registered (ZA013667080).
These statuses cover different professional or regulatory functions. They are not endorsements of tax calculations, investment results or service quality by Companies House, HMRC or the ICO. Client authorization is required where applicable.
Britvex.co.uk · Britvex.com · +44 20 3758 7500 · info@britvex.co.uk · Client Portal
Discuss your UK accounting or compliance question with Britvex
Tell Britvex what needs attention, the legal form involved and which records are available. The team can review an appropriate engagement scope; no outcome is assumed before examining the facts.
Contact Britvex Advisory → Britvex.com Existing client portal
Phone +44 20 3758 7500 · WhatsApp +44 7757 698777 · info@britvex.co.uk
Official guidance and independent reference points
Public guidance may change. Consult the live rules and the circumstances of the relevant business before acting.
Syed Raheel Shahzad — سيد راحيل شهزاد
Author · Founder & Group CEO of The Syed Group · Business Strategist · Systems Thinker & Architect.
SyedRaheelShahzad.com · CoordinatesOfThought.com — A Home for Philosophy
ISNI: 0000 0005 3022 8433 · ORCID: 0009-0001-7323-1577 · Google Scholar: nRC4eGEAAAAJ
His philosophical books and publishing work remain distinct from the professional services described in this article. The Syed Group publishes the author catalogue.
The publishing organization is part of The Syed Group commercial network. Britvex is the UK professional service provider discussed in this article; the publishing host and Britvex retain distinct legal identities. Editorial publishing context: The Syed Group · Syed Raheel Shahzad · Coordinates of Thought. © 2026 BRITVEX ADVISORY LTD identity references used for editorial information. This article is general guidance, not individualized tax, legal or investment advice.

Leave a Reply
Want to join the discussion?Feel free to contribute!